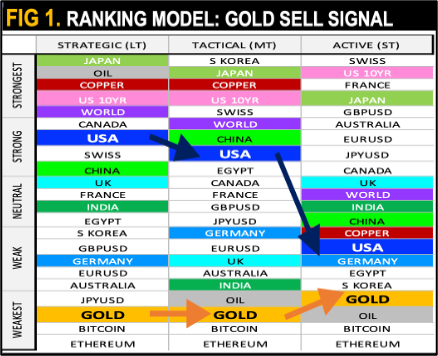
Gold recently generated a sell signal in the Global Ranking Model (Figure 1). This has come as a surprise, as the yellow metal proved one of our strongest convictions for the past two years. In fact, it became the primary holding and delivered a gain of 53% last year.
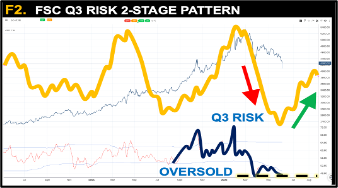
With such resilient performance, it’s important to stress that gold has not yet technically broken down and can cushion a healthy trend mean-reversion. In fact, the FSC timing model is signalling a 2-stage pattern into Q3, bottoming into July, then resuming higher (Figure 2).
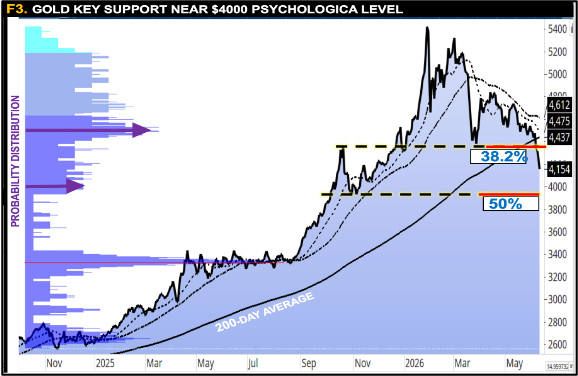
The price continues to make a pattern of sequential rising highs and lows above its long-term 200-day trend average. However, volatility within the asset class increased significantly. Gold has fallen approximately 25% from its all-time high, which is a substantial correction, but is nearing key psychological support at $4000. This also equates to a retracement of 50% of its trend over the last year or so (Figure 3).
In addition, our model does not rely solely on buy and sell signals. The objective is always to own the strongest-performing assets. If another asset class develops a superior trend and relative strength profile, we switch into it, even if the existing holding remains in an uptrend. Gold has therefore moved from the very strongest group of assets into a merely strong category. As a result, we have exited our position. It is entirely possible that the long-term trend in gold will accelerate again in the future. Should that occur, we would be happy to buy it back. Any future purchase would be treated as a new and separate investment from the previous holding.
Another newer signal is in the USA equity market. Here, caution is warranted. Market leadership has become extremely narrow, with gains concentrated in only a handful of giant companies with enormous market capitalisations. The broader market is considerably less impressive. While the model permits us to own this asset, we are maintaining tight stop-loss levels, especially as it has already dropped into a weak tactical trend ranking (Figure 1).
The other assets that currently rank highly are commodity-related investments, as part of the emerging super-cycle. Gold has been overtaken by silver and several industrial metals in terms of relative strength. We also note that food and agricultural prices remain firm, as part of broader commodity rotation and inflation effects. Moreover, the commodities are outperforming equities, in a generational cycle rotation. Seasonally, risk markets often experience weakness after the traditional “sell in May” (SIM) period, before entering the most dangerous phase of the year, which typically extends from late summer into October. Recall this includes mid-term election headwinds, as recently published.
So far, market behaviour is broadly following this Q3 seasonal pattern. The cyclical indicators we monitor suggest that any setback in the USA this year could be severe. While a rally may follow into the new year, we view such strength as temporary. Once that rally phase is complete, the broader bear market is likely to continue in a slow and extended fashion, potentially lasting until 2032.
For that reason, any current rally should be viewed as a short-term opportunity and managed with disciplined stop-loss levels. Like Warren Buffett, we believe there is value in maintaining liquidity. Preserving capital today ensures that we will have the resources available to take advantage of genuinely attractive opportunities when markets become cheap again in the years ahead.
Welcome feedback, likes and re-shares. Also remember to check our RWA premium services, for enhanced alpha performance, unique insights & proprietary market timing signals. Select link for more details: https://ronwilliam.substack.com/about
Robin Griffiths, FSTA
Robin Griffiths is Senior Advisor & Investment Strategist at RW Advisory.
Robin has served as Head of Multi-Asset Research & Advisory at the ECU Group. He was previously Chief Technical Strategist at HSBC Investment Bank for 20 years, before becoming Head of Global Asset Allocation at Rathbones, and then a director and technical strategist for Cazenove Capital Management. Robin was a Partner of WI Carr and Head of Technical Analysis at Grieveson Grant.
Robin is a committee member and former chairman of the International Federation of Technical Analysts, and former chairman, now fellow, of the British Society of Technical Analysts. Robin has been a member of ECU’s Global Macro Team for over 20 years. Robin has won several Technical Analyst awards for his research
Ron William, CFTe
Ron William is founder & CIO of RWA, an award-winning, macro-tactical, research and advisory firm, to a wide range of financial institutions & professionals, producing differentiated alpha, insightful idea generation and unique market timing.
He specialises in global, multi-asset, top-down framework, grounded in behavioural technical analysis, driven by cycles, based on the expanded “Roadmap” signature model of veteran market technician Robin Griffiths, originally published in Robin’s book “Mapping the Markets.” Additional insights also featured in their peer interview exchange hosted by Real Vision, T3 reports and Halkin letter contribution.
Driven by impactful education, Ron trains financial institutions and serves on the board of a variety of professional societies, notably as MENA director, education committee member of the International Federation of Technical Analysts (IFTA) and Development Director at the Foundation of the Study of Cycles (FSC).